
Your Food Brand Could Be Losing the GLP-1 Consumer Without Knowing It

GLP-1 medications are changing more than weight-loss conversations. They are beginning to change what consumers put in their grocery carts, which categories receive their spending, and what they expect from the food they buy. For food manufacturers, importers, and CPG brands, the question is no longer whether GLP-1s matter. It is whether your products still belong in the new grocery basket.
A major shift is taking place in the American grocery market, and it is happening quietly. Millions of consumers are now using GLP-1 medications, and their changing appetite and eating habits are beginning to influence what they purchase at the grocery store.
J.P. Morgan Global Research estimated that approximately 10 million Americans were using GLP-1 treatments in 2025 and projects that the U.S. patient population could reach roughly 25 million by 2030, with scenarios approaching 30 million depending on how the market develops. That is a consumer population large enough to have a meaningful impact on food and beverage categories.
The important point for food companies is that these consumers are not disappearing from the grocery store. They are still shopping. They are still buying food. They are simply becoming more selective about what goes into the basket.
Research into purchasing behavior is already showing signs of that shift. McKinsey, citing research from Cornell, found that six months after starting GLP-1 medications, spending declined across several indulgent categories, including chips and savory snacks, sweet bakery products, cookies, and soft drinks. At the same time, spending increased in categories such as yogurt, fresh produce, meat snacks, and nutrition bars.
For food brands, that creates a very different competitive environment.
Tim Forrest breaks down the growing impact of GLP-1 consumers on the food industry and why brands need to pay attention to where grocery spending is moving.
The video provides a quick look at the trend. But the larger story is worth understanding because this shift could affect everything from product development and packaging to retail positioning and U.S. market strategy.
GLP-1 Consumers Are Not Leaving the Grocery Store
One of the easiest ways to misunderstand this trend is to assume that consumers taking GLP-1 medications simply stop buying food.
That is not what the data suggests.
People still need to eat. They still prepare meals. They still shop for their families. They still purchase snacks, beverages, convenience foods, and ingredients. What appears to be changing is the composition of their grocery basket.
Research from AlixPartners found that households using GLP-1 medications reduced overall grocery spending by approximately 5% to 6% within six months of beginning treatment. Spending on savory snacks fell by roughly 11%, while sweet baked goods declined by about 7%.
Those numbers should get the attention of any food company that depends heavily on impulse purchases, indulgent snacks, large portions, or high-frequency consumption.
However, the more interesting part of the story is where that spending goes instead.
Consumers are increasingly looking for products that fit their changing eating habits. Protein, fiber, fresh produce, yogurt, prepared proteins, and other nutrient-focused foods are becoming more relevant to shoppers who are thinking differently about what they consume.
That means the food industry is not necessarily facing a shrinking consumer. It is facing a reallocated consumer.
The Grocery Basket Is Becoming More Intentional
For decades, food marketing has been built around the idea of encouraging consumers to eat more frequently and purchase more products. Snacks are positioned as convenient indulgences. Larger packages can communicate value. Promotions encourage consumers to stock up. New flavors create excitement and additional purchasing occasions.
GLP-1 medications introduce a different dynamic.
When appetite decreases, consumers may become more selective about how they spend their limited appetite. A shopper who previously bought several snack products may now purchase one. A consumer who once grabbed a sweet baked product on impulse may instead choose yogurt or fruit. Someone who previously purchased a large package may prefer a smaller portion.
This does not mean consumers suddenly stop enjoying food. It means the criteria for choosing food can change.
The product needs to feel worth the purchase.
That is particularly important for packaged food companies. If a consumer is eating less overall, every food choice can become more deliberate. The question becomes less about how much food can be sold and more about why the consumer should choose a particular product.
That is a significant change in the way brands need to think about value.
Snacks Are One of the Categories Feeling the Pressure
The snack aisle provides one of the clearest examples of what is happening.
AlixPartners’ research found that households using GLP-1 medications reduced spending on savory snacks by approximately 11% and sweet baked goods by about 7%. McKinsey’s analysis similarly found declines in chips, savory snacks, cookies, sweet bakery products, and soft drinks after consumers began using GLP-1 medications.
That does not mean the snack category is disappearing.
In fact, AlixPartners has described GLP-1 adoption as a significant headwind rather than an existential threat to the overall snack industry. Consumer behavior is influenced by many factors, and some consumers discontinue GLP-1 treatment or return to previous eating patterns.
The bigger issue is that snack companies may need to rethink which consumer need their products are satisfying.
A traditional snack may have been purchased primarily because it was convenient, indulgent, inexpensive, or satisfying in the moment. As consumer priorities change, brands may need to compete on additional attributes such as protein, fiber, portion size, ingredient quality, or nutritional value.
That does not mean every snack needs to become a protein product.
It means brands need to understand what consumers increasingly expect from the products they buy.
Protein Is Becoming a Bigger Part of the Conversation
Protein has been a major food trend for several years, but the growth of GLP-1 medications may add another reason for consumers to pay attention to it.
McKinsey’s research found increased spending in categories including yogurt, meat snacks, and nutrition bars among GLP-1 households. The broader grocery market is also showing strong consumer interest in specific functional benefits, including high-protein and low-sugar products.
For food manufacturers, this creates opportunities across a wide range of categories.
Protein can be incorporated into snacks, beverages, dairy products, cereals, frozen foods, baked goods, and prepared meals. Brands do not necessarily need to create an entirely new category to participate in the trend.
The opportunity may be as simple as identifying an existing consumer need and finding a better way to meet it.
For example, a snack company may explore a higher-protein formulation. A beverage company may develop a product with a stronger nutritional proposition. A cereal brand may emphasize protein and fiber. A food importer may identify an international product category that naturally aligns with the growing demand for nutrient-dense foods.
The important question is whether the product can deliver the benefit authentically and competitively.
Fiber May Be Another Major Opportunity
Protein gets a great deal of attention, but fiber deserves consideration as well.
Consumers are becoming more interested in foods that offer nutritional value beyond basic calories, and fiber is increasingly part of that conversation. This creates opportunities for food companies working with whole grains, legumes, fruits, vegetables, seeds, and other naturally fiber-rich ingredients.
It also creates opportunities for product innovation.
Brands can explore snacks, cereals, baked products, beverages, and other foods that incorporate meaningful sources of fiber while maintaining the taste, texture, convenience, and shelf life consumers expect.
The challenge is making the product genuinely appealing.
Consumers are not going to purchase a product repeatedly simply because it contains fiber. The product still needs to taste good, provide value, fit the consumer’s lifestyle, and perform well at the shelf.
That is where food innovation becomes important.
Fresh Foods Are Competing More Effectively for the Same Dollar
Another important part of the trend is the movement toward fresh foods.
McKinsey’s analysis found that spending on fresh produce increased among consumers using GLP-1 medications, while yogurt also saw growth.
For packaged food companies, this creates an interesting competitive challenge.
Your competitor may not always be another packaged product.
It could be fresh fruit.
It could be yogurt.
It could be a prepared protein.
It could be a smaller meal.
It could even be the consumer deciding not to purchase anything because they are less hungry.
That last point is particularly important.
The food industry has traditionally competed for share of stomach. When consumers are eating less, brands are forced to think more carefully about how they earn a place in that limited space.
The Consumer May Be Asking a Different Question
A consumer who is less hungry may look at a product differently.
Instead of asking, “Do I want this?” they may ask, “Is this worth eating?”
That distinction can have a major impact on product positioning.
A high-calorie snack may have been an easy purchase when appetite was high. A smaller, nutrient-dense snack may become more attractive when the consumer wants to make every eating occasion count.
This does not mean indulgence disappears. Consumers will continue to celebrate, socialize, enjoy treats, and purchase foods simply because they taste good.
But the balance can change.
That creates a challenge for brands whose entire proposition is built around excess, impulse, or frequent consumption.
It also creates an opportunity for brands that can combine flavor and enjoyment with attributes consumers increasingly value.
Food Brands Should Not Simply Put “GLP-1” on the Package
There is a temptation whenever a major trend emerges for brands to put the trend directly into their marketing.
That is not necessarily the right answer.
Food companies need to distinguish between responding to a consumer trend and exploiting a buzzword.
A product should not suddenly become a “GLP-1 food” simply because the marketing team sees an opportunity to attach the term to the packaging.
Instead, brands should focus on the underlying behavior.
Consumers using GLP-1 medications may be looking for smaller portions, higher protein, more nutrient-dense foods, convenient options, and products that fit into a reduced appetite.
Those are legitimate product and positioning considerations.
The brand does not necessarily need to mention GLP-1 medications at all.
It needs to deliver something the consumer actually wants.
Food companies should also be careful about health and medical claims. A packaged food product should not imply that it treats, prevents, or manages a medical condition simply because its target consumers happen to be taking medication.
The opportunity is in understanding consumer needs, not turning a food product into a pharmaceutical claim.
This Is a Major Opportunity for Food Importers
For food importers and international brands, changing U.S. consumer demand creates an interesting opportunity.
The United States already has a massive and highly competitive food market. Entering it successfully requires more than finding a product that sells well in another country.
Importers need to identify products that fit the U.S. consumer and the specific retail channels they are targeting.
As demand shifts toward protein, fiber, fresh foods, minimally processed products, and more intentional eating occasions, international brands operating in these categories may have an opportunity to bring something different to the American market.
That could include products based on traditional ingredients, high-protein foods, plant-based products, better-for-you snacks, nutrient-dense foods, or products built around whole-food ingredients.
But the opportunity still requires discipline.
The product must meet U.S. food regulations. Its label must be appropriate for the U.S. market. Ingredient and allergen information needs to be accurate. Import requirements need to be addressed. Suppliers need to be verified. Pricing needs to work after freight, duties, distribution, and other costs are considered.
And ultimately, the consumer needs a reason to buy it.
The Best Opportunity May Not Be a New Product
Food companies often assume that responding to a trend requires launching something new.
Not necessarily.
Sometimes the opportunity is already sitting inside the existing portfolio.
A brand may have a product with strong protein content but weak packaging communication. Another company may already have a high-fiber product that has never been positioned around that benefit. A snack manufacturer may have a smaller-format product that could become more relevant as consumers become more selective about portion sizes.
Before investing millions in new product development, companies should understand what they already have.
Review the portfolio.
Look at sales trends.
Analyze category performance.
Understand which products are gaining traction and which are losing relevance.
Then determine whether the problem is the formula, the packaging, the price, the positioning, the distribution, or the product itself.
Sometimes the product does not need to change.
The story around the product does.
Retailers Will Have to Adapt, Too
Food brands are not the only businesses affected by this shift.
Retailers are watching the same consumer behavior.
If shoppers begin purchasing fewer products in certain categories and shifting spending toward protein, fresh foods, yogurt, and other nutrient-focused products, retailers have to decide how their assortments should respond.
That can influence shelf space, new product introductions, private-label development, merchandising, promotional strategies, and category management.
For brands, this means the retail conversation may eventually change as well.
A buyer may not only ask how much a product sells today.
They may also want to know whether the product fits where consumer demand is going.
Brands that can clearly explain their relevance to changing consumer behavior may have a stronger story to tell in a competitive retail environment.
This Trend Is Bigger Than GLP-1 Medications
It would be a mistake to assume that GLP-1 medications are solely responsible for the food industry’s changing consumer behavior.
They are one part of a much larger shift.
Consumers are already paying closer attention to protein, sugar, ingredients, portion size, convenience, value, and perceived nutritional benefits. McKinsey’s broader grocery research found that nearly half of consumers prioritize specific functional benefits, such as high protein or low sugar, over general health positioning.
GLP-1 medications may accelerate some of those behaviors.
That is why food companies should look beyond the medication itself.
The bigger trend is intentional consumption.
Consumers are becoming more selective about where they spend their food dollars and what they expect to get in return.
That is a trend worth watching regardless of how quickly GLP-1 adoption grows.
What Food Brands Should Be Doing Now
The first step is not to panic.
It is to look at the data.
Food companies should examine their product portfolios and determine which categories are most exposed to changing consumer behavior. They should look at products that depend heavily on impulse purchases, indulgence, large portions, or frequent snacking.
At the same time, companies should identify where their existing products already align with emerging demand. Products with protein, fiber, convenient portions, strong ingredient stories, or nutrient-dense positioning may have opportunities that are not being fully utilized.
Companies developing new products should also consider these consumer trends before finalizing their formulas.
And international food brands planning to enter the United States should evaluate whether the products they are bringing into the market align with where U.S. consumer demand is moving.
This is not about chasing every trend.
It is about making sure your product strategy is based on where consumers are actually spending.
The Question Every Food Brand Should Be Asking
The wrong question is, “Are GLP-1 drugs going to destroy my category?”
The more useful question is, “What is changing about my customer, and does my product still give them a reason to buy?”
That question can lead to better decisions.
It can reveal products that need to be repositioned. It can identify categories worth entering. It can uncover opportunities for reformulation or new product development. It can even help an importer determine which international products deserve consideration for the U.S. market.
The consumer is still there.
The grocery trip is still happening.
The money is still being spent.
But the basket is changing.
Your Food Brand Could Be Losing the GLP-1 Consumer Without Knowing It
The biggest risk for food companies is not necessarily that GLP-1 consumers stop buying food.
It is that they stop buying your particular food.
If a shopper has less appetite and becomes more selective, every product in the basket has to earn its place. Products that provide convenience, taste, value, nutrition, and relevance have an opportunity to remain part of that basket.
Products that rely primarily on old purchasing habits may have a harder time.
This is why food companies need to look at GLP-1 adoption as more than a pharmaceutical story. It is becoming a consumer behavior story, a grocery story, and potentially a product development story.
The companies that understand the shift early can make informed decisions about their portfolios, positioning, retail strategy, and U.S. market opportunities.
The goal is not to chase the GLP-1 consumer.
It is to understand the consumer well enough to know where your product belongs as the market changes.
How Tim Forrest Consulting Helps Food Brands Navigate Changing Demand
Consumer behavior can change faster than a food company’s product development cycle. By the time a trend becomes obvious, a brand may already have packaging, inventory, suppliers, and distribution strategies built around yesterday’s consumer.
Tim Forrest Consulting helps food brands and importers evaluate their products against changing U.S. consumer demand while addressing the regulatory and market-entry requirements involved in bringing food products to American consumers.
That includes FDA compliance, FSMA requirements, import readiness, product positioning, retail strategy, distribution, and scalable brand growth.
For international food companies, the opportunity is not simply to bring a product into the United States. It is to determine whether that product is positioned for the consumer and retail environment it is entering.
Tim Forrest Consulting has guided food companies and importers since 1997 and has helped clients generate more than $1 billion in retail revenue, including placing 23 brands into Costco.
If you are a food entrepreneur, manufacturer, importer, or CPG brand trying to understand how GLP-1 adoption and changing consumer behavior could affect your product portfolio, now is the time to evaluate where your brand fits.
Book a call with Tim Forrest Markets: timforrestmarkets.com
The grocery store is not disappearing. The consumer is not disappearing. But the basket is changing, and food brands need to understand where the money is moving before their products get left behind.
 “Hi I’m Tim, and I love the food business! I’ve been helping large and small companies and entrepreneurs achieve success for decades. My consulting projects have contributed to major successes for my clients, including many with 100%+ year-over-year growth rates. I enjoy sharing my expertise, and hope you find these blog posts enlightening. Please reach out to me with any questions or comments.”
Share This Story
Related Posts


Let’s Talk

What We Do
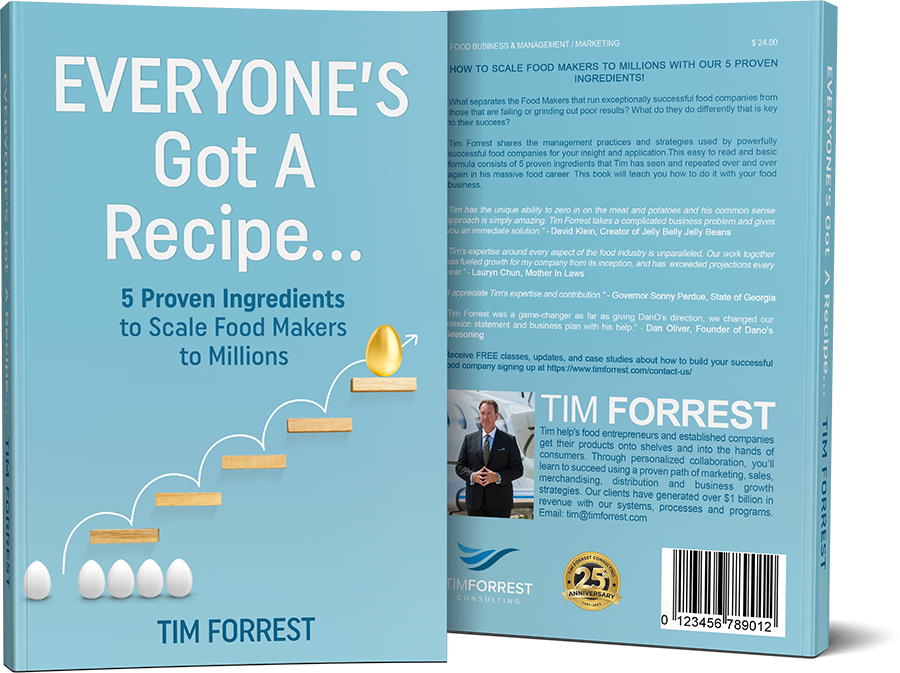
 We help food entrepreneurs and established companies get their products onto shelves and into the hands of consumers. Through personalized collaboration, you’ll learn to succeed using a proven path of marketing, sales, merchandising, distribution and business growth strategies. We’ve generated over $1 billion in revenue and company valuations for our clients. Let us put our expertise to work for you.


